Every loan officer has had the same daydream. It usually shows up around 9:40 on a Tuesday night, somewhere around the third reheated cup of coffee: What if I could just know?
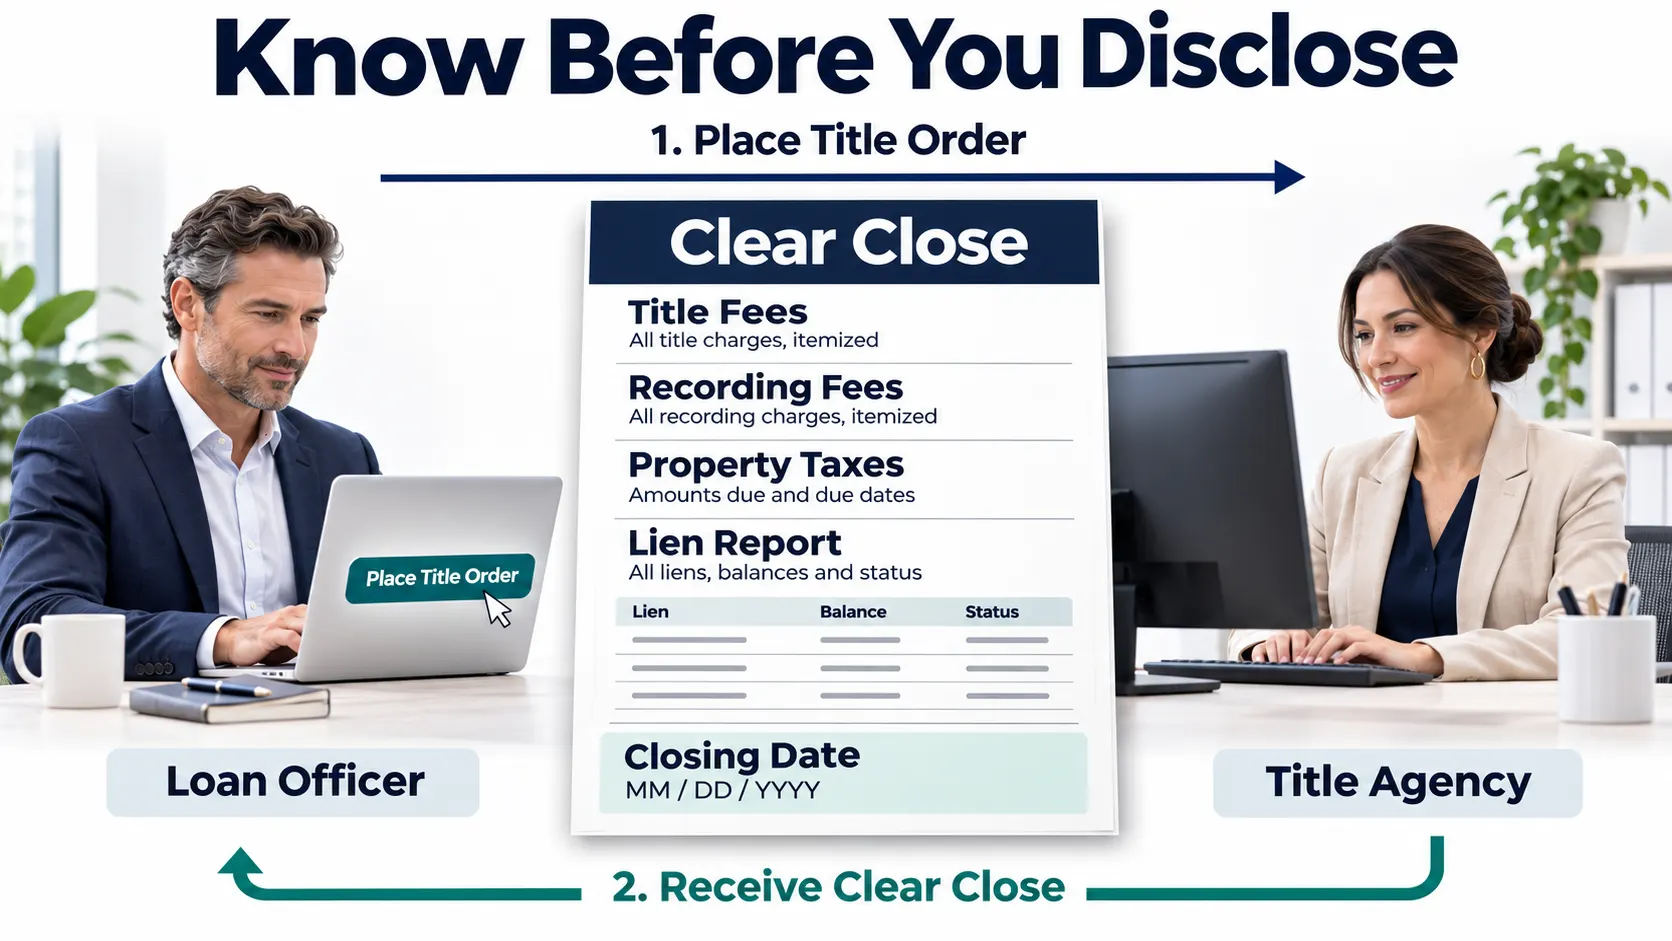
Know the title fees before the Loan Estimate goes out. Know whether an old lien is hiding on the property. Know when the deal will actually close. Not in week three. On day one, the moment you have a property address.
For most of this business’s history, that’s been a daydream. We think it’s time it became an ordinary Monday.
The Monday you already know
Meet Jordan, a loan officer licensed in four states. On Monday a past client calls, wanting to refinance and pull some cash out of their house for a new kitchen. Great borrower, solid equity, easy file.
Jordan pulls credit, estimates the title fees off a sheet she’s pretty sure is from this year, and sends the Loan Estimate. The client is thrilled.
Then week three arrives. The title commitment turns up a home equity line from 2019 that was paid off but never released, from a lender that has since merged with another bank. And the house is held in a family trust, which the borrowers forgot they’d set up.
The closing date slides. The rate lock gets nervous. The fees on the Closing Disclosure don’t match, and Jordan is doing math on a tolerance cure. Her client is now asking, very politely, what is going on.
None of it was Jordan’s fault. Every one of those problems was in the public record on day one. She just couldn’t see it.
Now, the other Monday
Same Jordan. Same client. This time, before sending anything, she types the property address into ClearClose with the loan amount and purpose. By the time she puts her coffee down, she has three answers.
Answer one: the price. Every title fee, endorsement, recording fee and transfer tax for that exact property, laid out the way the Loan Estimate wants them, from the title company that will actually close the file.
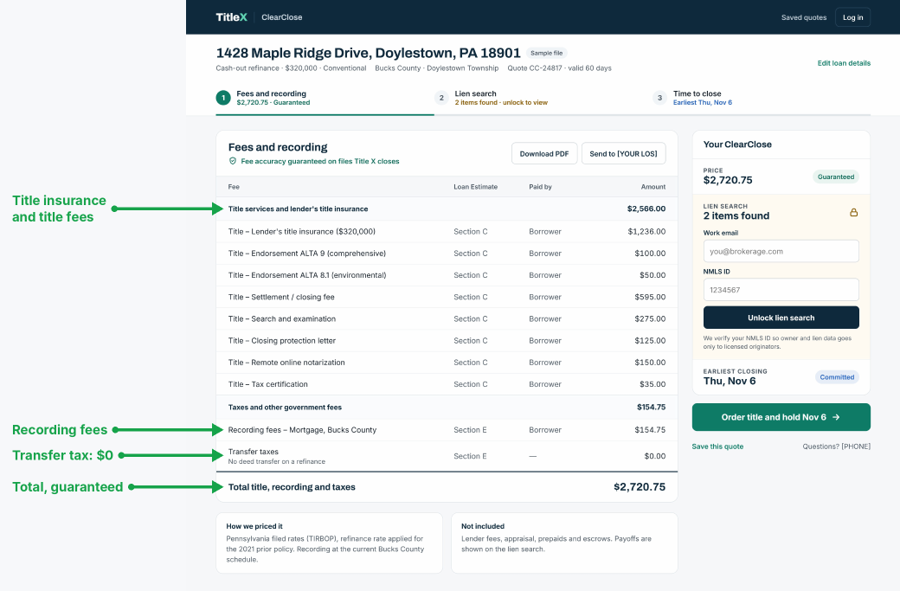
The price, mapped to the Loan Estimate. (Sample file.)
Answer two: the problems. A lien search of who owns the property and what’s recorded against it. It flags the 2019 line with no release, notices the trust and confirms the taxes are paid. Then it rates the file Green, Yellow or Red. Jordan’s comes back Yellow: closeable, with two items to clear.
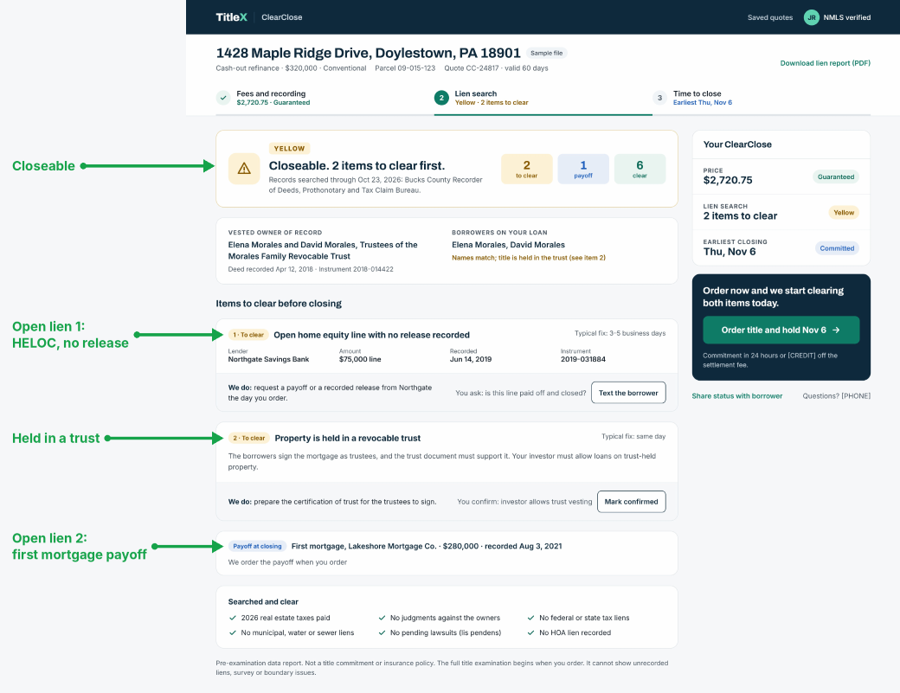
The problems, with what Title X does about each one. (Sample file.)
Answer three: the closing date. Based on what the lien search found, the county and the calendar, ClearClose gives a realistic closing date, one that already accounts for chasing down that old release.
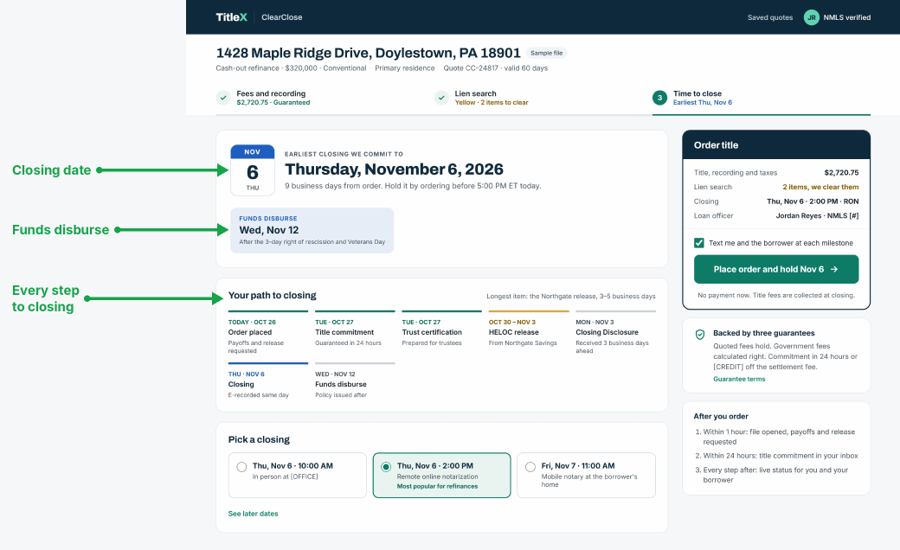
The closing date, and every step to get there. (Sample file.)
So on day one, Jordan calls her client: “Did you ever pay off that old home equity line? And is the house in a trust?”
“Oh! Yes, and yes. I totally forgot.”
That’s the whole drama. The release is requested on day one instead of day nineteen. The trust paperwork starts that afternoon. The fees match. The deal closes on the date Jordan promised. Nobody writes a blog post about a deal like that, and that’s exactly the point.
Why this matters now
With so many homeowners holding onto low first-mortgage rates, much of today’s business is home equity lines, cash-out refinances, and investor loans held in LLCs and trusts. Those are exactly the files where title surprises live. And when volume is tight, a deal that slips can cost you the client and the referral partner behind them.
What ClearClose is, and isn’t
ClearClose isn’t magic, and it doesn’t replace a title examination. The lien search is an early look at the public record, not a title commitment or insurance policy. A full examination still happens when you order, and some things, like an unrecorded lien or a boundary issue, won’t show up in any early search.
What it does is move the questions to the front of the file. And it comes from the people who actually close the loan: the company that quotes your fees, searches your property and commits to your date is the same one at the closing table.
The dream, made ordinary
A loan officer’s dream isn’t a flashy dashboard. It’s a Loan Estimate you trust, the right question on day one instead of an apology on day nineteen, and a closing on the date you promised.
The best deals are the boring ones. ClearClose is our way of making more of them boring.
About Title X
Title X is an AI-first title agency built for mortgage brokers and loan officers who lend across state lines. We put artificial intelligence to work on the slow parts of title, reading records, matching liens to their releases and flagging problems early, so our people can spend their time solving them. Every file runs through a Six Sigma process designed to remove errors and variation, so the hundredth closing is as clean as the first. Tech-forward and accountable, we quote it, search it and close it in 30 states. Learn more at www.titlexco.com.